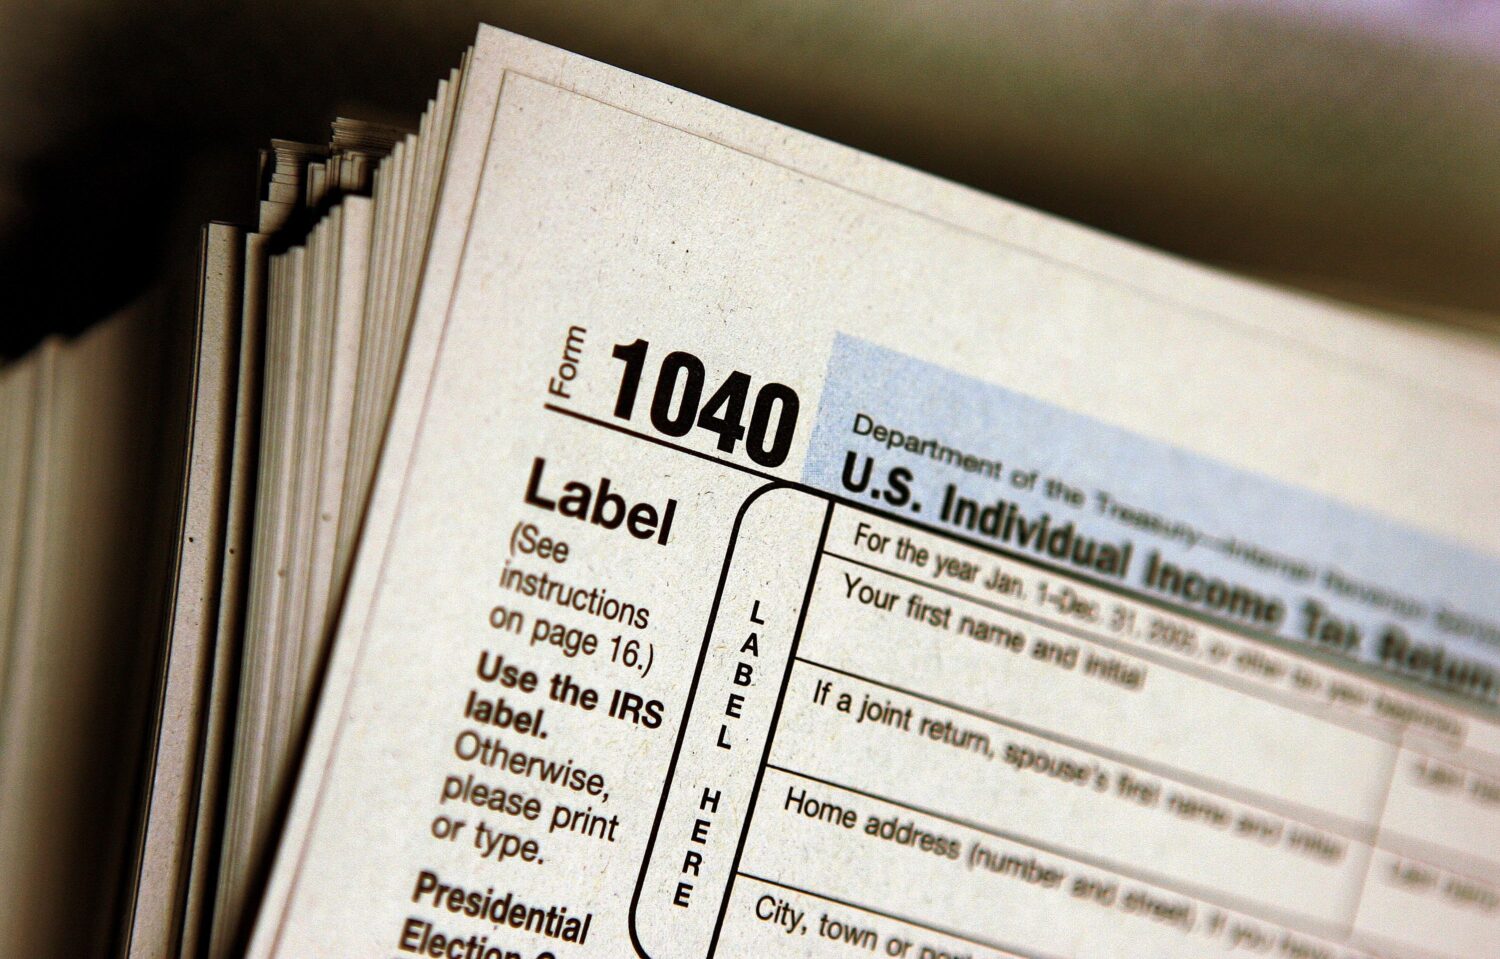
The quiet hum of a Tucson courtroom provided the backdrop for a profound reckoning that would strip away decades of professional trust and expose a meticulously woven web of deception. Darlene Musgrove, a 68-year-old tax preparer who had positioned herself as a benevolent guide for everyday Americans navigating the labyrinthine complexities of the Internal Revenue Service, found herself on the receiving end of federal justice. A jury convicted her on all 22 counts of preparing false federal income tax returns, a verdict that sent a clear, resounding message that the thin line between professional guidance and criminal fraud had been crossed with reckless abandon. The courtroom, filled with the subdued murmurs of reporters, the solemn faces of legal counsel, and the faint scent of aging paper and polished wood, heard the foreman read the verdict without a flicker of hesitation. For Musgrove, who had spent years behind a desk translating the financial lives of her neighbors into columns of numbers, the echo of that gavel signified an abrupt and devastating end to a career built on a foundation of sand. But beyond the legal jargon, the procedural formalities, and the stark statistics, this case is a deeply human tragedy, unfolding in the lives of ordinary people who sought professional assistance during the stressful tax season and instead received a betrayal so complete that it would threaten their financial security, their peace of mind, and their very standing with the law they never intended to break. They came to her seeking clarity and relief; they left carrying a burden of suspicion and fear that will likely linger for years.
The prosecution’s case hinged on the compelling, heartbreaking testimony of twelve of Musgrove’s former clients—individuals who took the stand not as accomplices, but as unwitting victims of a confidence scheme dressed in the impeccable attire of a professional tax office. With a mixture of raw confusion, indignation, and quiet tears, they recounted how they had gathered their W-2s, 1099s, mortgage interest statements, and various other financial documents, trusting her expertise to file their taxes accurately and lawfully. They sat in her waiting room, shared intimate details of their finances, and placed their faith in her promise to maximize their returns while staying on the right side of the law. However, when their returns were processed, they discovered deductions that they had never claimed, had no knowledge of, and could not substantiate. These were not minor rounding errors or mathematical slips; they were phantom deductions, likely fabricated as inflated charitable contributions that never happened, fictitious business expenses for ventures that never existed, or unreimbursed employee expenses that were entirely fictional. The clients testified emphatically that they were completely oblivious to these false claims, believing that the documents presented to them were an exact reflection of their financial year. They also noted the telltale, unsettling sign of the scheme: their refunds were significantly larger than those they had received in prior years. For some, this might have initially seemed like a stroke of incredible luck or the reward of a particularly savvy tax preparer, but for these individuals, it was the first chilling clue that something was profoundly wrong, leading them to question whether their trusted advisor had planted a ticking time bomb within their personal financial records, one that could detonate at any moment.
Underneath the dry legal charge of “preparing false returns” lies a chillingly calculated motive, one that the U.S. Attorney’s Office for the District of Arizona argued convincingly: the relentless pursuit of repeat business through the seductive allure of oversized refund checks. Musgrove’s strategy was a twisted, cynical form of customer retention, a business model built on deception rather than service. In the fiercely competitive market of tax preparation, where clients often chase the most substantial refund check without understanding the underlying mechanics, a preparer who consistently delivers larger returns becomes a highly sought-after commodity, almost a local legend. By injecting fabricated deductions into her clients’ returns, Musgrove artificially inflated their refunds, creating a false sense of value and fiscal reward that they had not legitimately earned. The clients, unaware of the illegality, were likely thrilled with her apparent “magic” touch, believing they had found a particularly aggressive and clever tax advocate who knew all the secret loopholes. This manufactured success generated intense loyalty, causing them to return year after year, and likely encouraging them to refer friends, family, and coworkers to her office. Musgrove understood the universal, deeply human desire to keep more of one’s hard-earned money, and she weaponized that desire, turning standard tax preparation into a fraudulent bonanza that enriched her practice while endangering her clients. This motive transforms the crime from a simple bookkeeping error into a premeditated conspiracy against both her clients and the federal treasury, a calculated gamble where the potential rewards of a loyal clientele were deemed worth the enormous risk of a federal investigation, an audit, and ultimately, a prison sentence.
The financial carnage left in the wake of Musgrove’s scheme is staggering, though the official number only tells a fraction of the harrowing story. According to the U.S. Attorney’s Office, the 22 false returns caused a total tax loss of approximately $127,166 to the U.S. government, money that should have been collected to fund roads, schools, public safety, and vital social services, but was instead artificially funneled into the pockets of taxpayers who did not legitimately deserve it, at least not in the inflated amounts they received. However, for the 22 victims, the true cost is exponentially higher and far more personal. They are now saddled with the terrifying prospect of IRS audits, back taxes, penalties, and interest payments that have likely compounded significantly since the initial false filings were submitted. The IRS holds taxpayers strictly accountable for the accuracy of their returns regardless of who prepared them, which means these unwitting clients may be forced to repay the fraudulent refunds, battling the agency’s formidable enforcement machine to prove their innocence while simultaneously dealing with the mountain of paperwork required to correct their tax history. The psychological toll is immense, as they face the social stigma of being associated with tax fraud, the financial strain of paying back money they never truly had (or money they have already spent), and the daunting task of rebuilding their financial reputations from scratch. For many, a simple act of seeking help has turned into a multi-year ordeal of legal battles, frantic phone calls to the IRS, and a constant, gnawing anxiety about whether their names will be permanently tarnished by a crime they did not commit.
This case serves as a stark and sobering reminder of the pervasive vulnerability that exists within the American tax preparation ecosystem, a system that relies heavily on trust in an increasingly complex regulatory environment. Each year, millions of taxpayers—many of them elderly, low-income, or simply unfamiliar with the ever-shifting tax code—hand over their most sensitive financial information to third-party preparers, doing so out of necessity, convenience, and an implicit faith in their professional competence. While the vast majority of tax preparers are honest, hardworking professionals who would never dream of risking their licenses, cases like Musgrove’s highlight the dangerous “audit lottery” dynamic, where unscrupulous preparers gamble that the IRS will not scrutinize their fabricated entries or cross-reference them with third-party data. For the clients, the lesson is brutally harsh: they are ultimately legally responsible for every single line item on their return, even if they never saw it, never understood it, or never authorized it. Musgrove’s betrayal is not merely a legal infraction; it is a profound breach of fiduciary duty, an exploitation of the vulnerable, and a corrosive erosion of the public’s trust in the financial professionals whose stated job is to safeguard their wellbeing. Her actions have cast a long, dark shadow over the entire tax preparation industry, making it harder for legitimate preparers to build trusting relationships and harder for clients to know whom they can reliably depend on, highlighting the critical need for rigorous due diligence, independent review of one’s own documents, and a cautious, skeptical eye on any refund amount that seems too good to be true.
As the dust settles on this unsettling chapter, Darlene Musgrove now awaits her sentencing, scheduled for February 23, 2027. Given her age and the nature of the crime, she faces a maximum statutory penalty of three years in prison and a fine of up to $100,000, though the actual sentence will depend on a comprehensive pre-sentence report, her criminal history, the severity of the loss, and the judge’s ultimate discretion. The distant date serves as a testament to the slow, methodical wheels of federal justice, allowing ample time for additional evidence gathering, victim impact statements, and a thorough review of the case’s mitigating and aggravating factors. Yet, the emotional and financial wounds inflicted by her actions are unlikely to heal so cleanly or so quickly. For the twelve clients who bravely took the stand to tell their stories, the conviction is a validation of their truth and a measure of vindication, but it cannot erase the sleepless nights, the frantic searches for old documents, or the damage done to their credit scores and financial futures. For the broader community, this case strips away the anonymity of tax literature and reveals the very human faces behind the statistical reports of fraud. It reinforces the absolute necessity for vigilance, urging every taxpayer to review their own returns with the same scrutiny they would apply to a binding legal contract, and to question preparers about every line item they don’t recognize. While the criminal justice system has spoken, the ultimate legacy of Musgrove’s misdeeds will be a powerful cautionary tale—a stark reminder that behind every line on a tax form, there is a life, a trust, and a fundamental expectation of honesty that, once broken, leaves a permanent and unhealing scar on both the victims and the collective trust of the community.