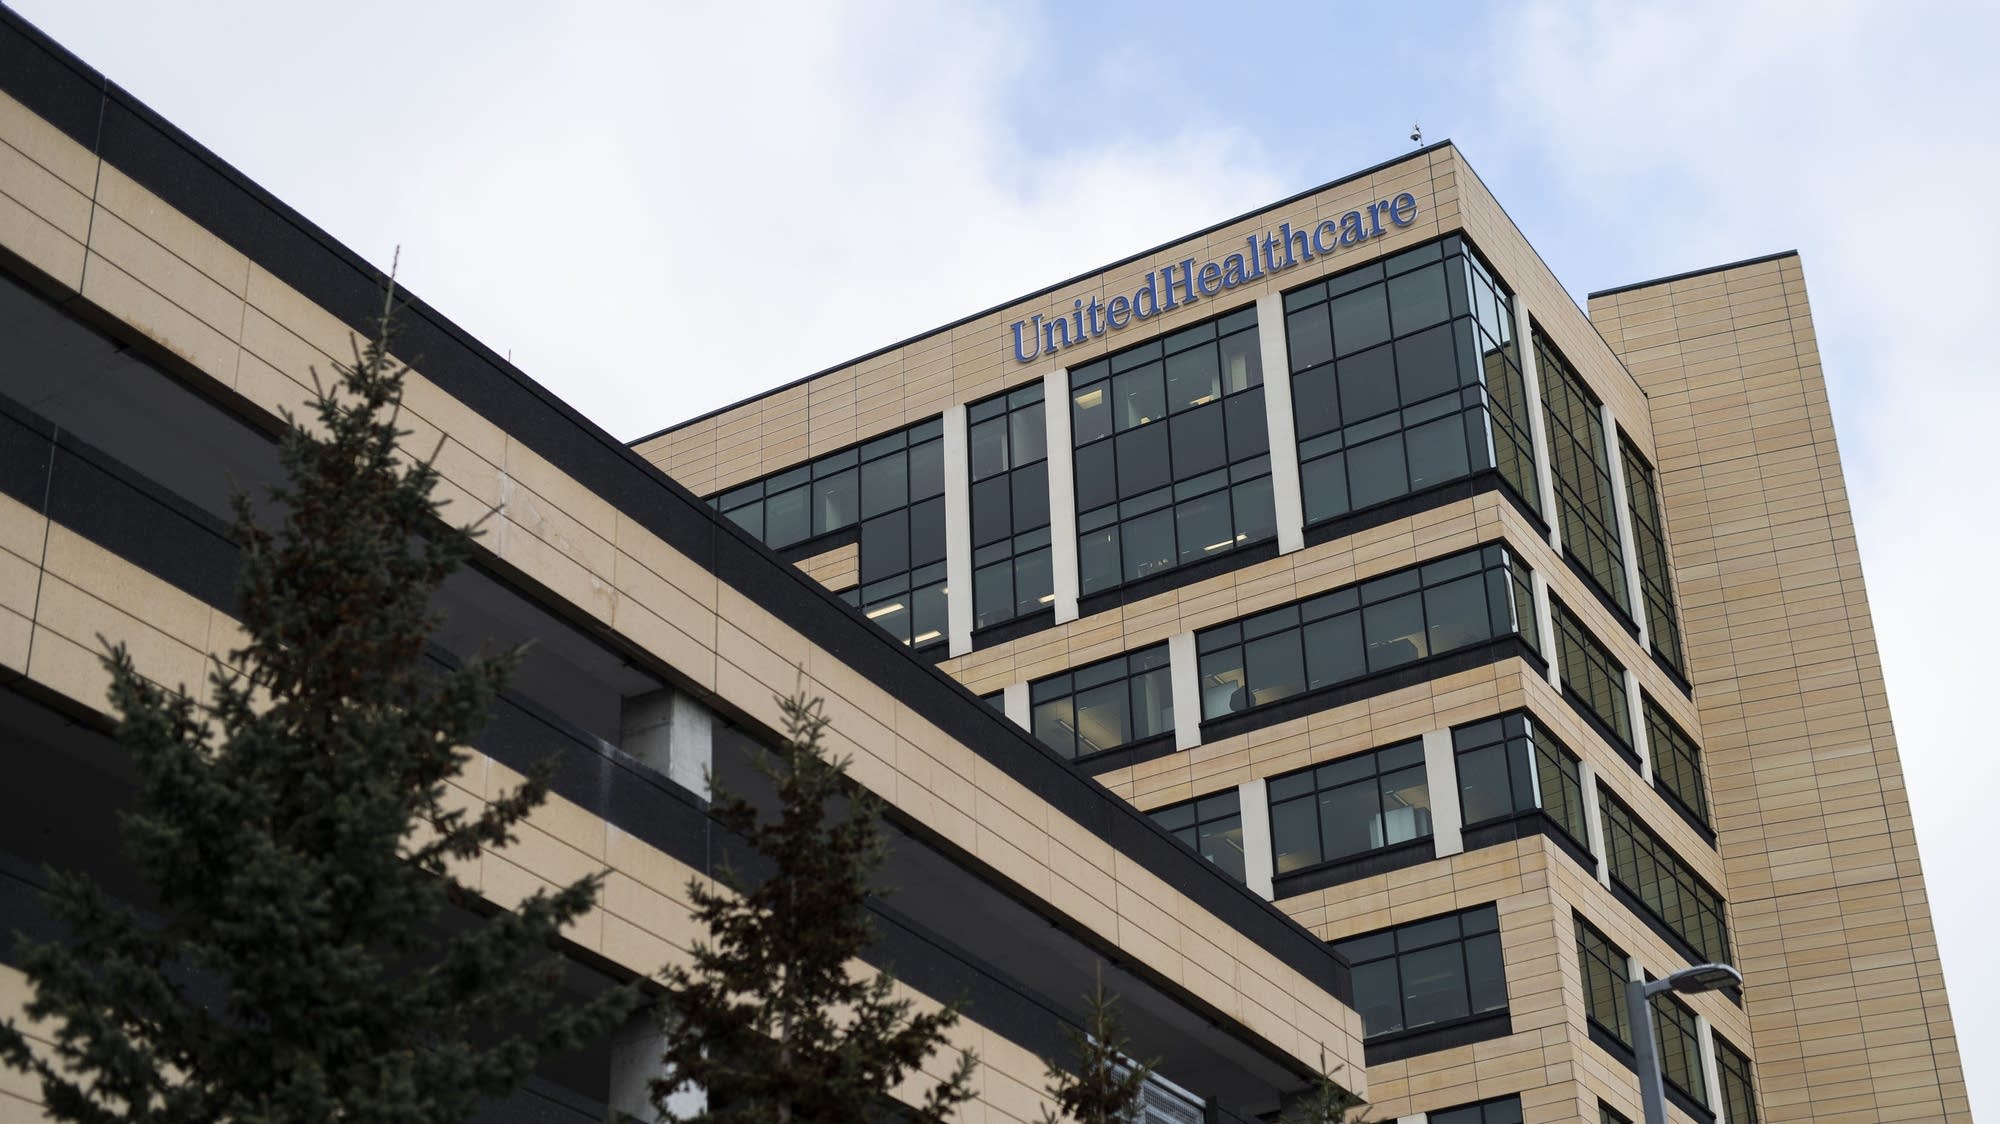
Every autumn, millions of older adults sit down at kitchen tables across the country with glossy brochures, mailers, and emails comparing Medicare Advantage plans. For many, the single most important question is simple: Will I still be able to see my doctor? Will my local hospital be covered? That question is now at the center of a legal battle in Minnesota. Fairview Health Services, a major Minneapolis-based health system with hospitals, clinics, and physicians throughout the region, has sued UnitedHealthcare, alleging that the nation’s largest health insurer is falsely advertising its 2027 Medicare Advantage plans. Fairview says it has chosen not to renew its contract with UnitedHealthcare, yet the insurer’s provider directories and plan materials still list Fairview hospitals and clinics as if they will be in-network in 2027. The lawsuit, filed in federal court in Minnesota, argues this is deeply unfair—especially because Medicare’s annual enrollment period is approaching and most people affected are seniors trying to make one of the most consequential health care decisions of the year. As the complaint puts it, Fairview’s current patients and Medicare beneficiaries shopping for coverage will be confused about whether Fairview is in-network with UHC, and they could lose the chance to choose a different plan for 2027 that would allow them to continue seeing providers at Fairview during the annual enrollment window. For a senior with a trusted primary care doctor, a cardiologist, or a cancer care team, losing access to those providers can feel like losing a lifeline. The annual enrollment period runs from October 15 through December 7, and if a plan’s provider directory is wrong, a patient may spend another full year paying more for care, traveling farther, or starting over with unfamiliar doctors. This isn’t just a contract dispute; it’s about whether people can trust what a health plan tells them when they are choosing coverage for the year ahead.
At the heart of the dispute is a fundamental disagreement about the status of negotiations. Fairview says it did not renew its contract with UnitedHealthcare in June, and that it is not currently in negotiations with the insurer and does not expect to reopen discussions. UnitedHealthcare, by contrast, says it is actively collaborating with Fairview in good faith to reach a mutually affordable agreement, while also trying to maintain long-term access for Fairview members. The company says that if an agreement cannot be reached, members will be notified about the possibility of Fairview going out of network, following the guidelines set by the Centers for Medicare and Medicaid Services. Fairview, however, argues that simply notifying members later is not enough. The harm happens now, during the enrollment period, when seniors are choosing plans. If a plan’s online directory says Fairview is in-network, a senior may select UnitedHealthcare over another plan, or may be allowed to automatically stay in UnitedHealthcare, only to discover after the enrollment deadline that Fairview is not covered. That kind of mistake is difficult to undo. Medicare Advantage plans are chosen annually, but the consequences of that choice can last for an entire year. Fairview’s lawsuit asks the court to step in before that harm occurs, not after the fact. The company says it has been communicating directly with patients about the Medicare Advantage change and providing resources to help them understand their coverage options ahead of the annual enrollment period. The gap between Fairview’s insistence that negotiations are over and UnitedHealthcare’s claim that it is still seeking a deal is not just a legal detail. For patients, it means the picture is confusing. They are being told by the health system to prepare for a change, while their insurer may be telling them that everything is still up in the air. That confusion is exactly what Fairview says makes the inaccurate directory so dangerous.
This lawsuit did not emerge from nowhere. According to the complaint, Fairview has encountered serious difficulties in its dealings with UnitedHealthcare Medicare Advantage plans for years. The list of grievances includes payment delays, low reimbursement rates, prior authorization challenges, and payment denials. These are not just bureaucratic annoyances. For a health system, they can be existential. When an insurer pays slowly or underpays, a hospital or clinic has to compensate with extra staff, repeated appeals, and financial pressure. When prior authorization is required, doctors have to spend valuable time getting permission from insurance companies before performing procedures, ordering tests, or prescribing treatments. If that permission is delayed, patients wait in pain and uncertainty. If it is denied, patients may have to try a different treatment, or pay more out of pocket. Fairview has not spelled out every example publicly, but the underlying message is clear: the relationship has become untenable. Choosing to walk away from a contract with a major insurer is not a decision any health system takes lightly. It affects revenue, administrative relationships, and patients who have grown comfortable with their medical homes. But Fairview says it can no longer participate in a system that, in its view, creates so much friction and financial strain. For seniors, that decision may be hard to understand, especially if they have been satisfied with their doctors. It is also a reminder that provider networks are not permanent. They are constantly negotiated and renegotiated behind the scenes, and when relationships break down, patients can be caught in the middle. Fairview’s decision suggests that the problems were not minor or occasional. They were serious enough that the health system was willing to risk losing tens of thousands of patients in order to make a point about how it wants to be treated.
The dispute came to a head in September. Fairview asked UnitedHealthcare to confirm that the health system would not be listed in provider directories for 2027. According to the lawsuit, UnitedHealthcare appeared surprised by the request and could not provide an answer. Fairview then asked for written confirmation that same day. In the days that followed, Fairview’s legal team sent UnitedHealthcare a notice stating that Fairview would not participate in the insurer’s Medicare Advantage plans in 2027. But when UnitedHealthcare sent out its annual notice of change, it directed enrollees to an online provider directory that, Fairview says, continued to list Fairview as an in-network provider for 2027. The annual notice also told members that if they did not select another plan, their enrollment would continue automatically. Fairview argues that combination is exactly what creates danger. A senior who is generally satisfied with UnitedHealthcare might ignore the annual notice, see that Fairview is still listed as in-network, and do nothing. Or a senior shopping for a new plan might choose UnitedHealthcare specifically because Fairview is in its directory. Either way, they will believe they have access to Fairview when they do not. Fairview estimates that roughly 33,000 of its current patients are enrolled in UnitedHealthcare Medicare Advantage plans each year. For those patients, this is not abstract. They might have an appointment scheduled at a Fairview clinic in November. They might have a surgery planned for January. They might rely on a Fairview specialist who knows their medical history and coordinates their care. If their plan does not cover Fairview, they may have to find new providers, travel farther, or pay significantly more. The loss of a trusted relationship with a doctor is not just an inconvenience; for many older adults it can cause real anxiety and even lead them to delay needed care. The company is asking the court to stop this before patients make decisions based on wrong information.
Fairview is asking a federal court for several forms of relief, and it wants some of that help immediately. The health system is seeking a temporary restraining order before Medicare’s annual enrollment period begins on October 15. The goal is simple: require UnitedHealthcare to correct its network information before seniors start making decisions. Fairview is also asking the court to require UnitedHealthcare to turn over profits it earns from Fairview patients who enroll in its Medicare Advantage plans for 2027, a type of remedy designed to remove any financial incentive for misleading listings. In addition, Fairview is seeking compensatory damages for the costs it has incurred in reaching out to Medicare patients about the change, including helping them understand their coverage options. The lawsuit is specific to Medicare Advantage plans offered by UnitedHealthcare. It does not affect Fairview’s separate commercial health insurance agreement with UnitedHealthcare. Patients who have UnitedHealthcare coverage through an employer will continue to have in-network access to Fairview in 2027. The distinction matters because many people receive UnitedHealthcare through their workplace and would not be affected by this Medicare Advantage dispute. But for Medicare beneficiaries, the stakes are high. Fairview has said it is communicating directly with patients about the change and providing resources to help them understand their coverage options ahead of annual enrollment, which runs from October 15 through December 7. Dr. Jaya Kumar, Fairview’s chief medical officer, said: “We are asking the court to require accurate information before enrollment begins, when patients still have the opportunity to make an informed choice.” That sentence captures the urgency. After December 7, most people cannot simply change to another plan. They may be locked into a plan for a full year, stuck with coverage that no longer includes the doctors and hospitals they once trusted.
This case is bigger than one health system and one insurer. It speaks to the role of trust in American health care, especially for older adults who are often making health care decisions under pressure. Medicare Advantage plans have become increasingly popular, in part because they bundle medical and drug coverage into a single plan and often include extra benefits like dental, vision, or fitness programs. But the plans are only as good as their provider networks. When a directory is inaccurate, it undermines the entire foundation of informed choice. Enrollment is not a trivial matter. It is a decision that affects access to doctors, hospitals, medications, and out-of-pocket costs for the next year. If UnitedHealthcare is allowed to keep Fairview listed as in-network, the harm may not be obvious immediately. It may surface in January, when a patient calls to make an appointment that once was covered and discovers it is not. It may surface in February, when a bill arrives for a procedure at a hospital the patient believed was covered. It may surface in March, when a senior realizes their specialist is now out of reach. That is why Fairview is asking the court to act now, before the enrollment window opens. It is not asking for a radical remedy; it is asking for accurate information. The company’s argument is straightforward: patients should be able to make decisions based on facts, not on outdated or misleading provider directories. For Minnesota seniors, the practical advice is also straightforward: don’t assume your plan will keep your providers. Check the plan’s network, call your doctor, and read the notice of change carefully. But relying on individual vigilance is not enough. The system should be honest by default. A health plan that lists doctors and hospitals it knows are leaving should not be allowed to keep them visible just to maintain enrollment numbers. Fairview’s lawsuit is a test of that principle. It asks the court to force transparency where transparency is lacking, and to protect the people who have the most to lose: the seniors who simply want to know that the doctor they trust will still be there when they need it.