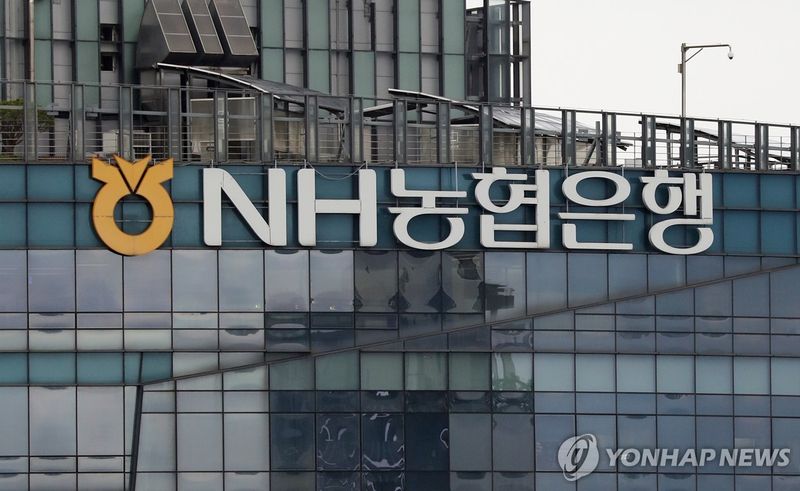
Trust is the quiet foundation of banking. Every time a customer makes a deposit or opens an account, they are making a bet that the institution on the other side will be honest, careful, and law-abiding. For NH NongHyup Bank, a major South Korean bank with deep ties to the country’s agricultural communities, that trust has been part of its identity for generations. It is the bank of rice farmers, cattle ranchers, and small-town cooperatives; the place where families keep their savings and businesses borrow to seed the next harvest. But trust, once damaged, is hard to restore. The Financial Supervisory Service has now issued a stark reminder that reputation cannot replace compliance. The FSS announced that it has imposed an institutional warning on NongHyup Bank for allegedly submitting false documents and systematically obstructing an official inspection. Institutional warnings are not minor fines or gentle suggestions. They are classified as severe disciplinary measures under the FSS’s sanction system, sitting just below the kinds of penalties that can suspend or shut down a financial institution. The notification, delivered on the 26th of last month by the FSS’s Anti-Money Laundering Office, cited document manipulation and other failures. The FSS also notified the bank of sanctions against individuals: pay cuts for six unregistered executives and employees, reprimands for seven, cautions for two, and two items requiring voluntary remediation. For a bank that has long positioned itself as the financial heart of rural Korea, this is more than a legal matter. It is a deep institutional wound, one that will require more than a statement of regret to heal. Customers may still see their balances, but they are entitled to ask: can we still believe what this bank tells us?
Last year, from April 8 to May 9, the FSS conducted a special inspection of NongHyup Bank’s anti-money laundering operations. The inspection team asked for customer verification records, the documents that prove the bank knows who its customers are and what they do. What happened next was chilling. A total of 22 employees from four teams accessed the bank’s anti-money laundering system and systematically manipulated or changed 27,808 customer verification records. They did not contact the customers to confirm their information. They did not ask branch employees who had opened the accounts. Instead, they altered the records and submitted them to the FSS as if they were genuine. The bank also arbitrarily omitted third-party customer verification details that the inspection team had specifically requested. This was not an accident, not a software glitch, not a few lazy employees. It was a coordinated operation, involving dozens of people and thousands of records over a short period. Think about what 27,808 records means. Each one represents a person, a name, an address, an occupation, a risk score. Each one was changed to conceal the truth from regulators. Customer verification is not bureaucratic paperwork. It is how a bank knows whom it is serving. Without accurate verification, criminals can hide behind fake identities, launder money, and finance illegal activities. By changing records, NongHyup did not merely break a rule; it made the entire system of financial oversight harder to enforce, and it did so knowingly. For the employees who took part, there may have been pressure to meet targets or hide past mistakes. But no workplace pressure justifies falsifying official documents. The sheer scale of the manipulation suggests that many people knew what was happening, and none of them stopped it.
The FSS went on to say that the bank obstructed the inspection itself. It restricted access to the anti-money laundering system, making it impossible for examiners to confirm the false submissions and omissions. This is almost worse than lying: it is actively preventing the truth from coming out. When a regulator arrives at a bank, the expectation is cooperation. Instead, NongHyup treated the inspection as an enemy to be defeated. And this was not an isolated incident. During a regular inspection in 2024, NongHyup Bank had also manipulated data entered into its computer systems and falsely submitted customer verification records. In other words, the bank developed a habit of treating inspections as obstacles to be overcome, not obligations to be met. The FSS’s decision to characterize the conduct as systematic is significant. It suggests this was not a few rogue employees acting on bad judgment, but a culture that tolerated, or even encouraged, concealment. Such a culture is corrosive. It reaches beyond compliance departments and shapes how the entire institution views the law. If a bank is willing to alter records to please an inspector, what else might it be willing to alter to please investors, or to hide losses, or to approve a risky loan? The purpose of anti-money laundering regulation is to keep the financial system transparent and accountable. When a bank obstructs an inspection, it is not just fighting with the regulator. It is telling the public that it has something to hide. The fact that top management may not have personally clicked the mouse does not let them off the hook. They create the incentives, the pressures, and the culture that make such behavior possible.
Beyond the manipulation, the inspection revealed fundamental failures in the bank’s anti-money laundering duties. During the period covered by the inspection, NongHyup Bank violated its customer verification obligations when opening new accounts through branches, non-face-to-face channels, or third parties, and when conducting one-off financial transactions. It changed additional information about customers at high risk of money laundering without verifying it. It did not increase scrutiny when those customers later returned to conduct other financial transactions. It also failed to report 30 large cash transactions of 10 million won or more made between January 2023 and March 2025 to the head of the Korea Financial Intelligence Unit. These are not complex or obscure rules. They are the basics of anti-money laundering. Financial institutions are required not only to verify identities but to monitor and report suspicious or unusually large transactions. By failing to do so, NongHyup potentially allowed money to move through the banking system without any oversight. The reporting requirement exists to help authorities trace illegal funds, whether from drug trafficking, corruption, or financial crime. Every unreported transaction is a missed chance to stop crime. More importantly, the bank’s failure to verify high-risk customers means it may have served people it knew nothing about, opening the door to abuse. Imagine a bank knowingly allowing a high-risk customer to deposit large sums without asking where the money came from. That is not just a technical violation. It is a breach of the social contract that gives banks the privilege of holding public money. Every bank is a gatekeeper between the legitimate economy and the shadows. When a bank stops checking who is coming through the gate, it is no longer a protector; it becomes a facilitator.
The FSS did not stop with an institutional warning. It took aim at individuals. Six unregistered executives and employees were ordered to take pay cuts. Seven received reprimands. Two received cautions. And the bank was given two items requiring voluntary remediation. These sanctions may seem modest, but they have real consequences. Pay cuts hit wallets. Reprimands go on employment records. And for executives, being publicly associated with a regulatory sanction can harm careers long after the issue has faded from the news. The FSS also notified the bank of nine institutional improvement measures. This is a clear call to fix the way the bank operates, not just to punish the past. The distinction between unregistered executives and regular employees matters. In South Korea, certain executives at financial institutions are required to be registered with supervisors, reflecting their responsibility for managing risk. An unregistered executive is someone who exercises senior authority without going through that formal accountability. When such people are punished for anti-money laundering failures, it sends a message: responsibility cannot be hidden behind office titles or organizational charts. The fact that the FSS named both executives and employees is also important. It shows that the manipulations were not confined to one level of the bank. They involved teams of people, across multiple departments, working together. The FSS’s sanctions are meant to deter future misconduct, not only at NongHyup but across the financial industry. It wants bankers everywhere to understand that manipulating records and obstructing inspections will be met with serious disciplinary action, and that individuals, not just institutions, will pay a price. For NongHyup, the next step is to implement the improvement measures honestly and transparently. That means changing systems, retraining staff, strengthening oversight, and, most importantly, creating an atmosphere in which employees can raise concerns without fear.
This episode is a sobering reminder that compliance is not an obstacle to good banking; it is the essence of it. A bank that manipulates records and blocks inspectors cannot be trusted with the savings of ordinary people. NongHyup Bank has serious work ahead. It must cooperate fully with regulators, discipline those responsible, and implement the nine improvement measures with genuine commitment. But beyond the technical fixes, the bank needs a cultural change. It must move from a mindset of how do we get through an inspection to how do we live up to our obligations. The trust of customers is not automatic; it is earned every day through honest behavior. For the farmers, shopkeepers, and rural families who depend on NongHyup, this is not an abstract regulatory issue. They need a bank that is safe, honest, and accountable. The institutional warning should be a wake-up call, not just for NongHyup but for the entire financial industry. If a respected institution can fall into this pattern of deception, others may be tempted to do the same. The FSS’s action shows that such behavior will not be tolerated. Now it is up to NongHyup to prove that it can rebuild what it has damaged and become the trustworthy institution it once claimed to be. Rebuilding trust will take time, perhaps years. It will require a visible commitment at every level, from the boardroom to the branch. It will require admitting mistakes, not just in legal filings but in the way the bank treats its customers and its employees. And it will require something rarer than systems and procedures: humility. Only after the bank openly confronts its failures and changes its culture can it hope to look its customers in the eye and say, honestly, that it deserves their trust again.