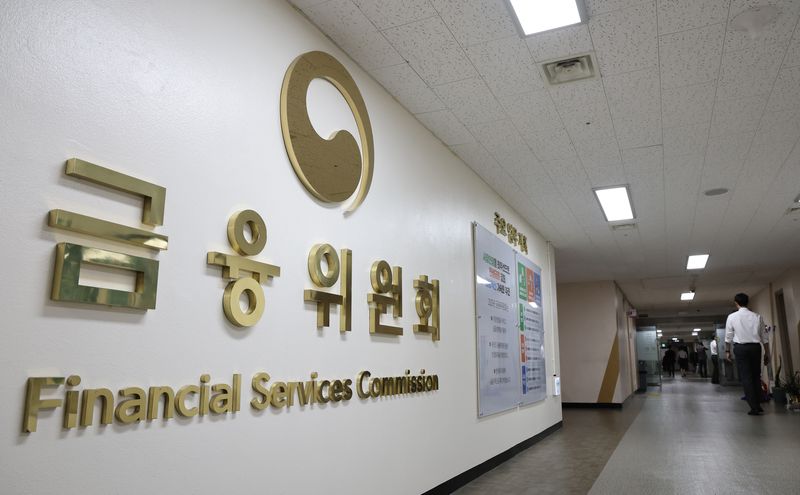
The news hit the Korean housing market like a sudden squall. On a seemingly ordinary Monday, a document began circulating through online communities and messaging apps with the kind of urgency that makes hearts race and phone lines light up. Titled “Draft Announcement of Additional Measures to Stabilize the Housing Market,” it claimed to have a planned release date of mid-November, and it was packed with what looked like official, authoritative details. It spoke of new land transaction permit zones in Gyeonggi Province, tightened lending rules for first-time homebuyers, and stricter guarantee requirements for jeonse (Charter) loans. For anyone navigating the already brutal landscape of Korean real estate, the text felt like a thunderclap. But within hours, the Financial Services Commission (FSC) stepped forward to douse the flames of panic. The rumor, they said, was entirely false. Not merely exaggerated or speculative, but a completely fabricated document of unknown origin, designed to mislead. And beyond simply correcting the record, the FSC signaled its intent to escalate matters, announcing it would request a formal investigation into suspected obstruction of official duties by deceptive means. In other words, someone was going to be held accountable for the anxiety and chaos they had unleashed.
To truly understand the sting of this rumor, one has to look at its content, which was crafted with a level of specificity that made it feel authentic. The fake document didn’t just wave vaguely at “market stabilization”; it laid out a detailed matrix of punitive measures. It claimed that specific areas of Gyeonggi Province would be newly designated as regulated zones, automatically subjecting them to stricter loan-to-value and debt-to-service ratios. It also proposed new hurdles for first-time buyers, suggesting that their access to financing would be severely curtailed. Perhaps most alarmingly, it introduced a draconian set of loan caps tied to home prices. For homes priced above 2.5 billion won, the document claimed the government would completely eliminate the existing loan ceiling of up to 200 million won, effectively banning mortgages outright at that price point. For homes valued between 1.5 billion and 2.5 billion won, the alleged plan was to slash the cap from 400 million won down to a mere 200 million won. The document even went further, detailing changes to jeonse loan guarantee ratios based on whether a household already owned property. The sheer volume of numbers, thresholds, and legal-sounding terminology was impressive in its own way. It mimicked the structure of actual government releases, right down to the bureaucratic phrasing, making it nearly indistinguishable from a real directive. That verisimilitude was precisely what made it so dangerous, and so infuriating to officials who woke up to a mountain of confused and frightened inquiries.
For context, the actual current mortgage rules in Korea are already quite restrictive by global standards, but they are not as absolute as the rumor suggested. Under the real framework, for homes in the Seoul metropolitan area and other regulated zones, a mortgage for a property with a market price of 1.5 billion won or less can reach up to 600 million won. For homes priced above 1.5 billion won and up to 2.5 billion won, the ceiling drops to 400 million won. And for the most expensive properties, those above 2.5 billion won, the limit stands at 200 million won. The fabricated document cleverly kept these price brackets intact—a subtle nod to realism—but then claimed that every single tier would be cut by an additional 200 million won. It was a half-truth twisted into a full-blown fiction. But this was not the first time such a tactic was used. Only weeks earlier, on the 20th of last month, a similar post with the title “Additional Mortgage Regulations in the Works” had made the rounds. That one claimed mortgages would be banned entirely for any home priced at or above 1.5 billion won, and that loans for cheaper properties would be slashed to between 200 million and 400 million won. The FSC had responded then with a clarification statement, labeling the claims baseless. Yet here they were again, facing a new iteration of the same corrosive fake news, this time weaponized with even more detailed—and therefore more convincing—specifics.
What is particularly striking about this episode is not just the denial, but the institutional resolve behind it. The FSC is not treating this as an isolated nuisance. They have officially requested investigations into the spread of this false information, invoking charges of obstruction of official duties by deceptive means, among other offenses. An FSC official noted that this is part of a persistent pattern, explaining that they had already requested investigations into similar posts in February, June, and October of this year on the same suspicion. This is a serious criminal charge in Korea, typically applied to those who interfere with government work through fraud or deception. The logic is that by creating a false narrative about imminent regulations, these rumor-mongers force the government to divert resources toward damage control, disrupting the orderly process of policy announcement and implementation. The Ministry of Land, Infrastructure and Transport issued a parallel statement, echoing the FSC’s words and confirming that its own investigations into identical or similar posts from February, June, and October were already underway. The coordination between the two ministries sends a clear message: the government is exhausted by this recurring tactic and is now moving from reactive rebukes to proactive legal action.
Behind this institutional anger lies a broader political and economic strategy that the rumors are actively threatening. The current administration, led by President Lee Jae Myung, has staked its credibility on a resolute, almost single-minded policy known as “supply at all costs.” The theory is simple: the only sustainable way to tame runaway housing prices is to flood the market with enough new homes to meet demand, thereby breaking the psychological expectation of perpetual price increases. This is not a policy of tweaking loan limits or adjusting tax burdens; it is a comprehensive effort to accelerate construction approvals, streamline permitting processes, and fast-track the development of new towns. Any fake news about sudden, punitive loan restrictions undermines this narrative. It shifts the public’s attention from the long-term promise of supply expansion to the immediate fear of financing shortfalls. It creates an atmosphere of urgency and panic, which often leads to ill-considered buying decisions—the exact opposite of the calm, rational market that the government wants to cultivate. When the FSC says the rumors are an obstruction of official duties, they are speaking to this strategic disruption. The rumors do not merely misinform; they actively sabotage the government’s message, its timeline, and its goals.
President Lee Jae Myung has been unambiguous about this vision in his public communication. In a post on X (formerly Twitter) on the 3rd, he delivered a striking declaration: “The myth that real estate never loses is now due to be shattered, and we must make sure it is.” It is a provocative statement, aimed squarely at the deeply ingrained Korean belief that property is the safest and most reliable investment. He went on to argue that with permits and approvals returning to normal under his administration, the so-called “supply cliff”—a period of severe shortage caused by years of stalled construction—would begin to ease around 2028. He concluded with a reaffirmation of the government’s commitment to the “supply at all costs” doctrine. His actions back up his words. On the 20th of last month, President Lee personally visited the Gyeyang area in Incheon, a site slated for development as a Third-Generation New Town. There, in a moment that captured the intensity of his administration, he described the situation as an emergency, urging officials to “bring supply forward as much as possible.” In this context, the fabricated rumors are more than just annoying; they are an assault on the very foundations of the administration’s economic narrative. For the average Korean citizen, this entire episode is a stark reminder of the delicate tightrope between market anxiety and official policy, and the ease with which a single anonymous post on the internet can shatter confidence, distort public discourse, and force the full weight of the government into emergency response mode.