Paragraph 1: The Quiet Temptation and the Hidden Epidemic
We all know that little twinge of temptation that can creep in after a minor fender-bender. You’re sitting in your car, a bit shaken, looking at the crumpled bumper, and a sneaky thought crosses your mind: “Well, my neck does feel a little stiff… maybe I can get a bit of compensation for the pain and suffering on top of the repair costs?” It starts so innocently, with a small exaggeration. But for the insurance industry, these seemingly harmless little white lies are the gateway to a multi-billion-dollar criminal enterprise that impacts every single driver on the road. Think about it—when someone files a fake claim, the insurance company doesn’t just eat the loss. They pass that cost right back to you through higher premiums. Essentially, every time an honest driver pays their bill, they are inadvertently subsidizing the pathological liar who staged a crash in a parking lot. The problem is so pervasive that it has become a game of cat-and-mouse, where fraudsters constantly devise new, increasingly brazen schemes to exploit loopholes in the system. However, as highlighted in recent industry analyses, including the insights from the New Straits Times, the scales are beginning to tip. We are entering a new era where the battleground is no longer just the physical asphalt of a crash site, but the digital ether of data. Artificial Intelligence and digital forensics have moved from the realms of sci-fi and police procedurals into the core strategy of insurance defense, offering a powerful, sophisticated, and highly effective arsenal against those who seek to game the system.
Paragraph 2: The Anatomy of Deceit and Its Financial Toll
To truly appreciate the weaponry being deployed, we must first understand the enemy. Motor insurance fraud is not a monolithic crime; it’s a spectrum of deceit ranging from opportunistic padding to organized, premeditated criminal rackets. On one end, you have the “opportunist” who adds a few extra repairs to an existing claim or exaggerates the damage to a pre-existing dent. On the other end, you have highly organized crime syndicates that stage elaborate “ghost accidents”—collisions involving vehicles that don’t exist, or using a real car but with fake passengers who claim whiplash. There are even documented cases of “crash for cash” rings, where fraudsters deliberately slam their vehicles into innocent drivers, distracting them, and then submitting massive injury claims. The financial hemorrhage is staggering. Globally, the insurance sector loses hundreds of billions of dollars annually to fraudulent claims, with motor insurance being the hardest hit. In any given market, it is estimated that a significant percentage—sometimes as high as 10% of all claims—contain an element of fraudulent activity. This creates a toxic cycle: higher operational costs for insurers, expensive legal battles, and inflated premiums for the law-abiding public. It also fucks up the emergency services, who have to respond to fake accidents, pulling resources away from actual emergencies. For a long time, investigators relied on gut feeling, a thorough adjuster’s intuition, and physical surveillance. But fraudsters are adaptive; they study the claims process just as carefully as the insurers do, making the old methods insufficient. The need for a new, untapped intelligence source became critical—and that source is the massive sea of data that modern vehicles and smartphones generate every second.
Paragraph 3: The Iron Eye of Artificial Intelligence in Pattern Recognition
This is where Artificial Intelligence steps into the spotlight, functioning as an indefatigable, hyper-observant claims adjuster that never sleeps. Contrary to popular fear, AI isn’t here to replace human judgment; it is here to supercharge it. The primary power of AI in this arena lies in its ability to process “linked data” and recognize anomalous patterns across thousands, even millions, of claims in a fraction of a second. Traditionally, an adjuster might notice a suspicious claim because of a gut feeling—maybe the timing was too perfect, or the story had holes. AI takes this intuition and turns it into hard algorithmic science. It examines dozens of variables simultaneously: the time of day the accident occurred, the weather conditions, the precise GPS location, the driving history of the claimant, the repair shop’s billing patterns, and the claimant’s social media activity. For instance, the AI might flag a claim where a severe “whiplash” injury is reported, yet the telematics data from the car shows the vehicle was traveling at a mere 5 mph at the point of impact. Or, it might detect a ring of fraud by noticing that five separate cars crash at the exact same remote intersection every month, always using the same towing service and the same body shop. AI can build “social link matrices” connecting claimants, attorneys, and medical clinics, revealing a crime network that human eyes would miss. It’s like a digital Sherlock Holmes, connecting the dots across a sprawling map of seemingly unrelated incidents to uncover a hidden conspiracy.
Paragraph 4: Digital Forensics—Letting the Vehicle Speak the Unvarnished Truth
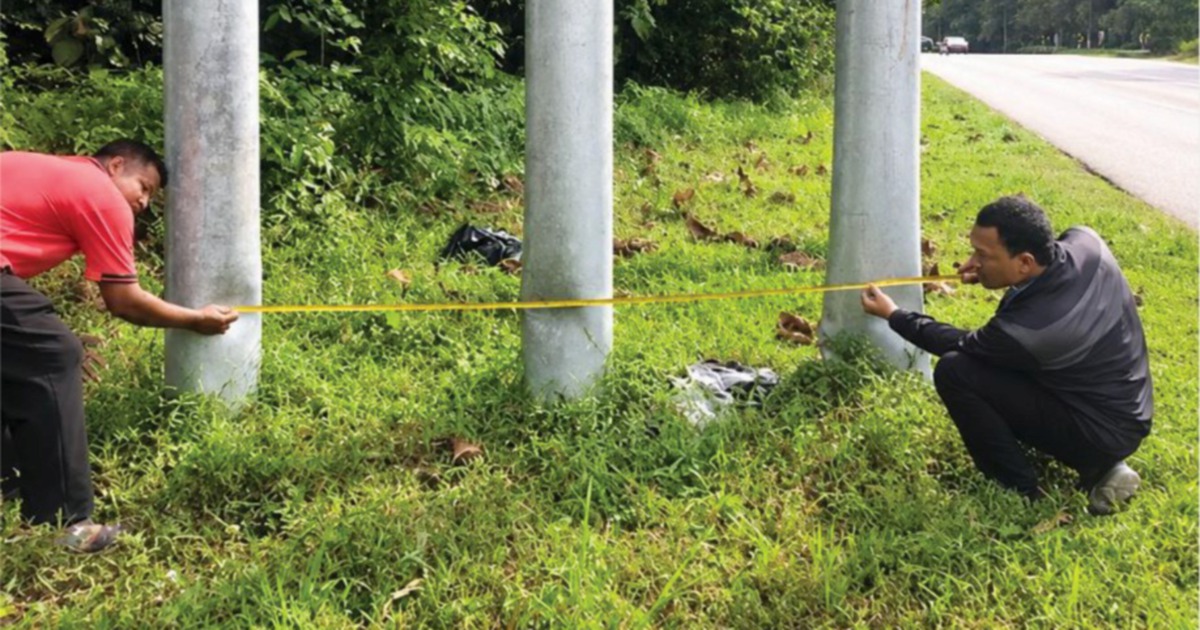
While AI provides the suspicion, digital forensics provides the irrefutable proof. This is the CSI aspect of the operation, where the very technology in our cars and phones becomes a silent, faithful witness to the truth. Modern vehicles are rolling supercomputers, packed with sensors and Event Data Recorders—think of them as the car’s “black box.” These devices meticulously record a vast array of data in the seconds leading up to, during, and after a collision: exact speed, throttle position, brake force, steering angles, and even whether the seatbelts were fastened. This data is nearly impossible to falsify. If a claimant states they were rear-ended at a traffic light, but the EDR reveals the accelerator was floored and the vehicle was actually in reverse, the story falls apart instantly. Beyond the car, there is the smartphone. Digital forensics experts can subpoena and analyze cell-site location information (CSLI) or GPS data to prove that a claimant was actually miles away at the time of the supposed crash, or safely tucked in bed. They can even analyze the metadata of accident “selfies” sent to insurers—revealing when the photo was actually taken, the exact device used, and the GPS coordinates, exposing inconsistencies in the timeline. Even more granular, forensic teams can analyze the wear patterns of the tires from a crash scene or the