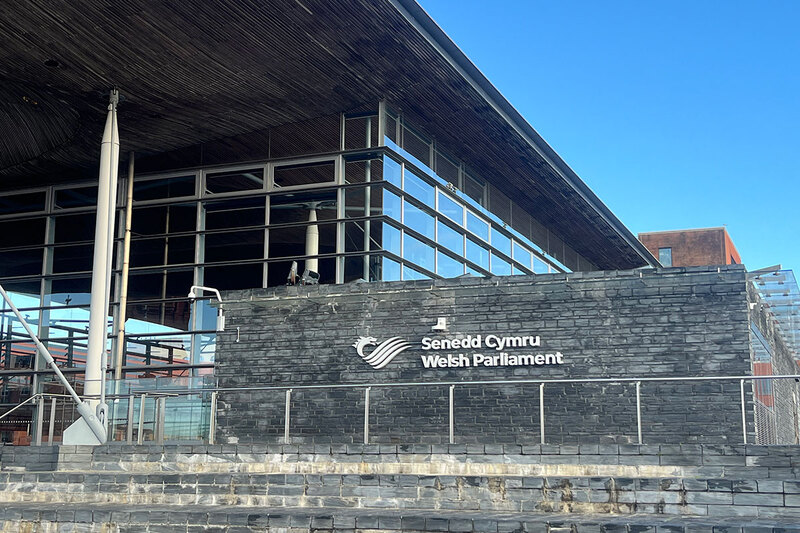
When we talk about the housing crisis, it is easy to disappear into spreadsheets, percentages and policy jargon. But behind every number is a life, a family, a set of choices made under pressure. Consider a simple question: where do you live, and how did you get there? For people born in Wales, the answer to that question looks very different from the answer for people who arrived from outside the UK, according to Senedd research. The census found that a higher proportion of people born in Wales live in social housing than those born outside the UK: 17.9% compared to 13.7%. At the same time, the private rented sector plays a much bigger role for people born outside the UK, with 35.9% of them renting privately, while only 12% of people born in Wales do. These numbers are not just abstract statistics. They tell a story about how housing opportunities are unevenly distributed, how recent arrivals often have no choice but to rely on a more expensive and less secure part of the market, and how “home” means different things depending on where you came from and when you arrived.
There is another layer to this story, one that speaks to the experience of immigrants themselves. The Senedd’s research briefing noted that among the 22,054 people who had lived in the UK for less than two years, a striking 68.7% lived in private rented housing. That makes sense if you think about what it means to arrive in a new country. You might not have a credit history, savings, a guarantor, or a support network. You cannot simply walk into a bank and get a mortgage, and applying for social housing can feel like waiting for a lottery you did not know you had entered. The private rented sector is often the only door that is open, even if that door leads to high rents and uncertain tenancy. But the research also found something hopeful: the likelihood of living in social housing or owning your own home increased with the length of time someone had lived in the UK. This suggests that integration is a process, not an instant event. People gradually put down roots, find stable work, build relationships, and eventually gain access to more secure housing options. The data also quietly undermines the unpleasant myth that immigrants are given special treatment or jump the housing queue. In fact, people born in Wales are more likely to live in social housing than people born outside the UK. The real problem is not “them” versus “us.” It is a housing market that is broken for almost everyone, even if it breaks differently for different groups. There is, however, one group the research flags as a particular source of pressure: asylum seekers. They make up a small proportion of migrants overall, but the design of the asylum system and significant gaps in data create specific challenges for Welsh local authorities. These are people who are not choosing where to live, who have no access to ordinary housing options while their claims are processed, and whose presence often lands on local services without warning or enough funding. The question is not whether we should have asylum seekers in Wales; it is whether our systems are ready to treat them fairly without throwing local housing markets into confusion.
Behind these individual experiences lies the uncomfortable truth that Wales simply does not have enough homes. The Senedd’s researchers put it plainly: decades of underbuilding have left Wales with a structural shortage of homes. This is not a small blip that a new policy tweak can smooth over. It is a deep, generational hole in the housing supply. And it changes the way we should think about demand. For years, politicians and commentators have pointed at population growth as the main reason house prices keep rising. But the briefing found that population growth alone does not explain what has happened. Some areas with very slow population growth still experienced sharp increases in house prices. What does that tell us? It tells us that demand is not just about numbers of people. It is about how wealth moves through society, who can borrow money and at what interest rates, how homes are treated as investments, and where people with money choose to park it. If a town loses population but house prices still go up, it is hard to argue that the problem is simply too many people chasing too few homes. More likely, it is too much money chasing homes as assets. People are not just buying homes to live in; they are buying them as savings accounts, retirement plans, rental income, and speculative bets. This fuels a market where prices become disconnected from local incomes, and ordinary working households are locked out of areas that were once affordable. The result is a generation of people who have given up on the idea of owning a home, but also struggle to find secure renting. Supply matters, absolutely. But we cannot pretend that simply building more homes is enough, especially if the new homes are luxury flats sold to overseas investors or second-homes that sit empty for eleven months a year. The housing problem is not one problem. It is a knot of interlocking issues, and pulling on one thread without looking at the others will not untie it.
Researchers who study this knot tend to focus on two big explanations for why housing has become so unaffordable. The first is planning rules. These rules were originally designed to protect the countryside, manage urban growth, and make sure new developments have the infrastructure to support them. But they also create additional costs and delays. Getting permission to build can take years, and those costs are ultimately passed on to buyers and renters. This is not an argument that planning rules are useless or should be abolished; it is an argument that the current system is time-consuming, unpredictable, and weighted in favour of those who can afford to hire expensive lawyers and consultants. The second explanation is what researchers call the “financialisation” of housing. That is a cold economic term for something quite simple: housing is increasingly treated as a financial asset rather than as a place to live. When a house becomes an asset, the important thing is not whether it provides good shelter but whether its value goes up over time. Investors buy homes not for the joy of a secure family home but for the promise of rising prices. This has huge consequences. It inflates prices beyond what any reasonable measure of affordability would suggest. It incentivises buy-to-let landlords to extract rent rather than maintain properties. It turns housing into a commodity to be traded, like gold or shares. In such a system, homes can sit empty as speculative investments while people sleep rough in the same city. And once housing enters the financial system, it becomes linked to global interest rates, international capital flows and the whims of global markets. No local council can simply decide to ignore those forces. But that does not mean local and regional governments are powerless. The key takeaway from the researchers, and arguably the most important sentence in the whole briefing, is this: the housing crisis is not one problem with one fix. It is a set of connected systems that must be understood and addressed together.
For the Welsh Government, that means being honest about what tools it actually has. The researchers said Wales’s ability to influence housing outcomes is strongest on the supply side. This includes planning policy, land assembly, and investment in social housing. In other words, Wales can decide what gets built, where, at what density, and whether it is affordable or not. It can buy land, take land into public ownership, and insist that a certain percentage of new developments meet local needs. It can invest directly in new social homes, and many have argued it should do so at a much greater rate than it does currently. These are powerful tools. Ultimately, housing has to be built somewhere, and local authorities are the ones who decide where. That is not nothing. But the briefing also points out that many of the most important drivers of demand sit outside Wales’s control. Interest rates are set by the Bank of England, not by the Senedd. Immigration rules are decided in Westminster, not Cardiff. And the global financial system does not stop at the Welsh border. When interest rates rise, mortgage costs rise, and that filters through the entire economy. When immigration policy changes, it can suddenly increase or decrease demand for housing in particular areas. When global capital floods into residential property, it pushes up prices in cities and beauty spots regardless of what local planners want. This does not mean Wales should give up. It means that policy cannot do everything on its own. The briefing is rather blunt about the limits of devolved power: Welsh policy can reshape supply over time, but it cannot fully control the demand pressures that interact with it. This is a crucial message for anyone who wants an easy answer or a soundbite. It is also a message that requires humility from all sides. The UK Government cannot solve the housing crisis alone, because it does not fully control the supply side or the local factors that shape communities. And the Welsh Government cannot solve it alone, because it cannot print money, set interest rates, or block the global movement of capital.
So where does that leave us? It leaves us with a need for a grown-up conversation, one that accepts complexity rather than escaping into slogans. We need to build more homes, especially social homes, and we need to build them well, in sustainable communities with schools, transport and green spaces. But we also need to think about the way we treat housing as a commodity. That means questioning the assumption that every property should be an investment opportunity, that owning a second home is somehow a harmless hobby, and that landlords should be able to extract maximum profit from families who have no other options. It means looking at the tax system, the planning system, the welfare system, and the banking system as parts of a whole, and asking whether they are pulling in the same direction. It means recognising that housing is not just another market. It is the foundation on which people build their lives. Without a decent home, children struggle to study, workers struggle to hold down jobs, and people struggle to stay healthy. The Senedd researchers did not offer a single magic solution because there is not one. But they did offer something almost as valuable: an honest analysis of how all these different forces interact. They showed that migrants are not the problem, that population growth is not an inevitable doom, and that the answer does not lie in blaming any one group or any one level of government. Rather, the answer lies in understanding that housing sits at the intersection of social justice, economic policy and human dignity. It is a right, not a reward. And if there is any hope for the future, it comes from that understanding. Because when we finally stop arguing about who deserves a home, and instead accept that everyone needs one, we can start looking at the whole system together. Then, and only then, might we build a Wales where the door is open for everyone.