Late Tuesday, in a Reno meeting room that had all the procedural gravity of a corporate election and all the narrative tension of a business epic, Caesars Entertainment shareholders made a decision that will likely reshape the company for years to come. They approved a $17.6 billion merger with Fertitta Entertainment, the Houston-based holding company run by billionaire investor Tilman Fertitta. The vote took place at a special meeting at the Eldorado Resort in Reno, where shareholders participated in person or through mail-in proxies, and the results were formally disclosed in a Securities and Exchange Commission filing Wednesday morning. According to Caesars, 65.4 percent of the shareholders participating in the meeting voted in favor of the deal, while the shares represented by those voters accounted for more than 70 percent of the company’s outstanding stock, comfortably exceeding the quorum requirement. For anyone who had held Caesars stock through the months of speculation leading up to this moment, the most important number was simple: each share would be converted into $31. That price represented a 49 percent premium over where the stock was trading on Feb. 25, before the market had a chance to digest Fertitta’s offer. In an era when shareholders are often asked to accept vague promises and long-term visions, this transaction offered something far more tangible—a fixed, generous price and a clear exit. The vote was the first major milestone in a multibillion-dollar process, but it was not the finish line. It was, however, the moment when talk became official, and when Caesars lovers, employees, and rivals all had to accept that the company’s future belonged to someone new. The special meeting may have looked like a formality, but in the casino business, where ownership changes have historically been as dramatic as the buildings themselves, this was a genuinely tectonic event.
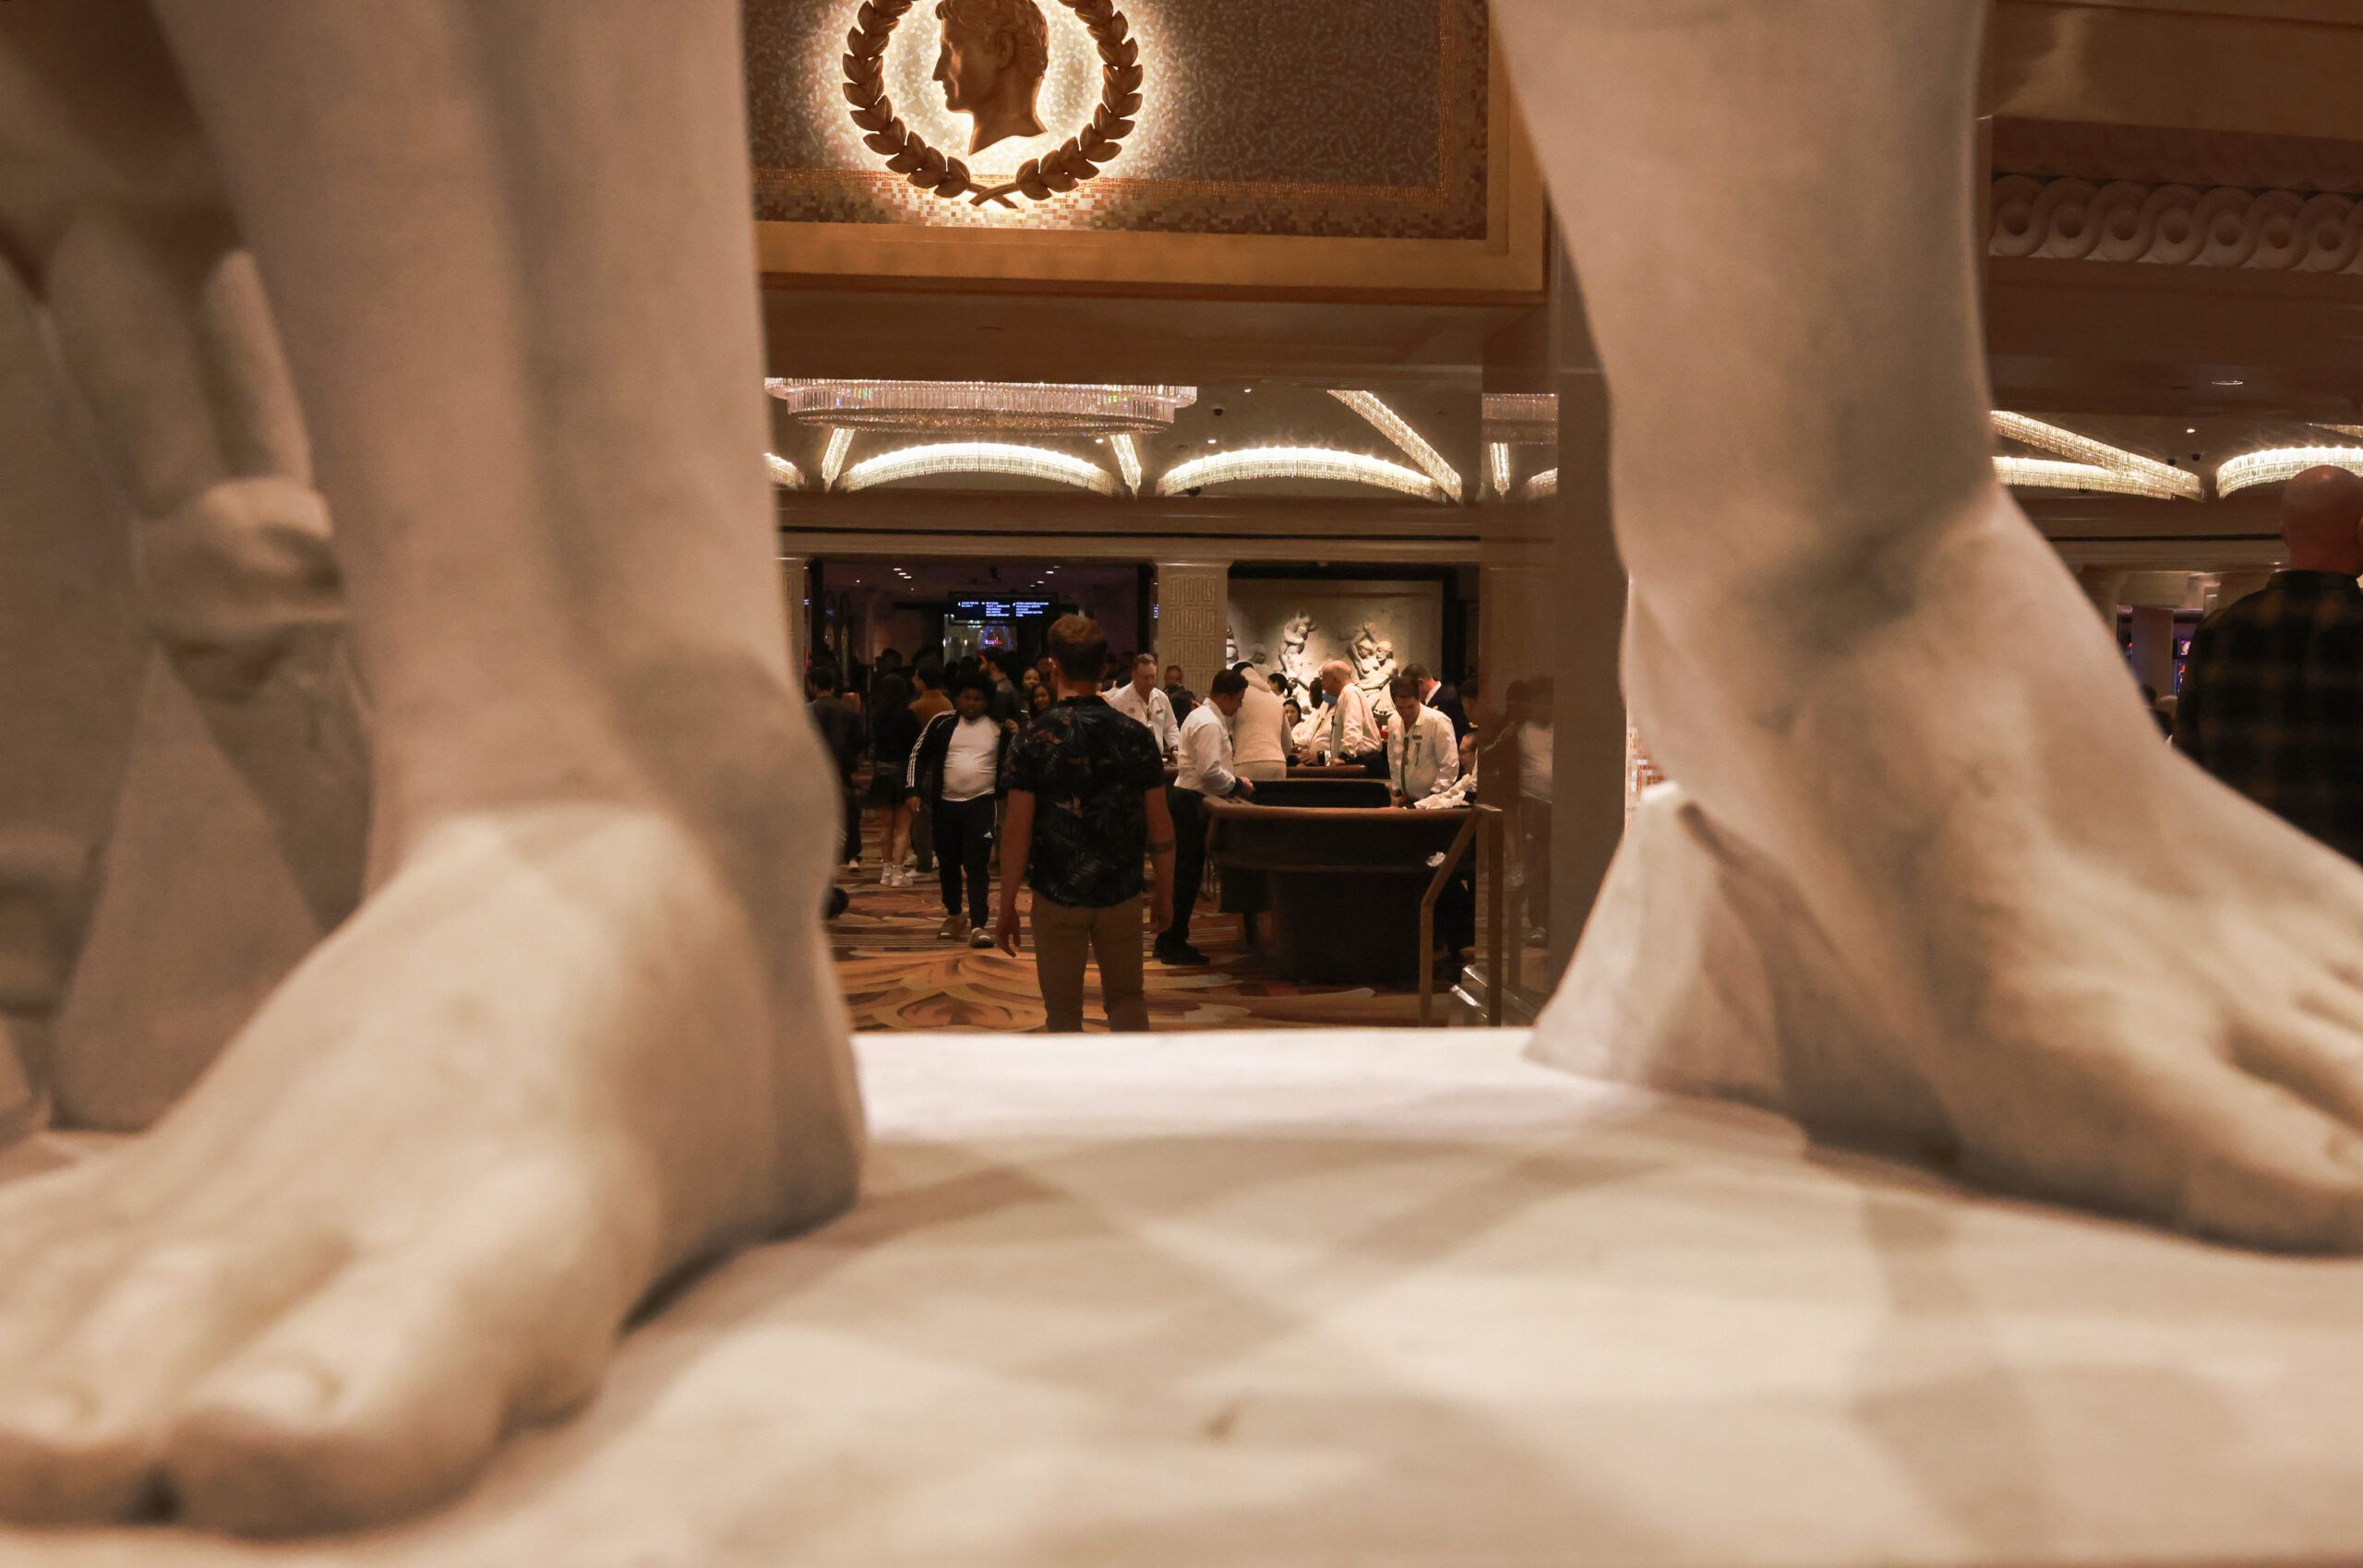
To understand what that vote means, it helps to know something about the man behind the other side of the table. Tilman Fertitta is not a quiet, anonymous Wall Street fund manager who appears only in quarterly letters to investors. He is a Houston-based entrepreneur whose name is attached to an empire spanning restaurants, hotels, casinos, and professional sports. His company, Fertitta Entertainment, controls roughly 600 businesses, including eight Golden Nugget casinos across five states. The Golden Nugget brand has long held a special place in the gaming world, offering a slightly more intimate, approachable alternative to the mega-resort glare of the Las Vegas Strip, while still delivering a serious casino experience. Fertitta’s personal fortune is estimated at $11 billion by Forbes, a figure that puts him in the upper echelon of American wealth and gives him the kind of financial firepower that can make a $17.6 billion transaction feel not just plausible but inevitable. In a remarkable twist, he is currently serving as the United States ambassador to Italy and San Marino, a diplomatic post that seems light-years away from the smoky gaming rooms and high-limit tables he knows so well. He also owns the NBA’s Houston Rockets, a high-profile asset that has taught him how to manage the spotlight, handle million-dollar egos, and keep the public entertained. Fertitta has always been an operator, not just an investor. He builds, manages, and brands things with his own instincts. Combining his Golden Nugget properties with Caesars—whose name still evokes Roman columns, toga-clad icons, and decades of Las Vegas history—will require blending two different cultures. The vote by Caesars shareholders suggests they believe he is the right person to do that. For employees, the change means learning a new boss’s playbook. For rivals, it means facing a beefed-up competitor with an appetite for growth. And for Fertitta himself, it means another chance to prove that his particular blend of hospitality savvy and bottom-line discipline can work at a scale few others have ever attempted.
Zoom out, and the scale of the combined company is genuinely striking. If the deal receives all necessary approvals, the merged operation would own or control roughly 60 casinos nationwide, including 15 resorts in Nevada. That alone would make the combined entity one of the largest gaming operators in the United States, with a footprint stretching from the desert to the shore. But the deal is especially consequential in specific local markets where the overlap between Caesars and Golden Nugget properties is hardest to ignore. At Stateline, the small Nevada community on the south shore of Lake Tahoe, the combined company would control three of the four casinos: Golden Nugget Lake Tahoe, Harrah’s Lake Tahoe, and Caesars Republic. In Laughlin, the river town known for its affordable resorts and Colorado River sunsets, three of the eight casinos would fall under the same corporate umbrella: Harrah’s Laughlin, Tropicana Laughlin, and Golden Nugget Laughlin. For travelers, this could be a subtle shift at first. The signs on the buildings would not all change overnight, and the loyalty programs that keep regulars coming back would take time to integrate. But the competitive dynamic would be radically different. Instead of several independent companies fighting for the same riverfront foot traffic or the same Lake Tahoe travelers, one owner would be managing a portfolio of neighboring properties. That can create efficiencies in marketing, housekeeping, entertainment booking, and staffing. It can also raise questions about whether the concentration of ownership in a particular town reduces competition and gives the landlord, as it were, too much control over the local casino economy. Regulators will look closely at precisely these questions in the months ahead. For local residents and long-time visitors, the logic of the deal is easy to understand but not always easy to love. A casino town with fewer owners is a different kind of place, even if the slot machines still ring and the buffets still open at the same hours.
For all the momentum generated by the shareholder vote, this is still only the first act of a long process. The merger must now run a gauntlet of regulatory reviews. Gaming regulators across the country, including the Nevada Gaming Control Board and the Nevada Gaming Commission, will scrutinize the deal with the kind of care that only people who regulate casinos can muster. They will examine Fertitta’s financial history, the sources of his money, his business associations, and his plans for the properties. They will want to know who the key executives are, how the new company will be structured, and whether anyone involved has a background that could embarrass the state’s gaming industry. At the federal level, there are also antitrust questions to consider. The combined company would have a particularly strong presence in certain markets, and regulators will have to decide whether that presence undoes the very competition that makes American gambling so competitive. Most state regulatory matters are expected to extend into next year, which means months of hearings, background investigations, and legal filings still lie ahead. For Caesars employees, this period is a strange limbo. The name on the door may not change tomorrow, but everyone knows that a new owner is coming. Budget decisions, hiring plans, and property upgrades all take on a temporary quality. Investors, meanwhile, have already been promised a fixed price, so their journey is largely complete. The regulatory approval process is not a rubber stamp. It is the system working the way it was designed to work, especially in an industry where public trust and regulatory confidence are not optional extras but essential conditions of doing business. Fertitta’s status as the U.S. ambassador to Italy and San Marino adds an unusual political flavor to the story, because he is simultaneously a diplomat and a dealmaker, a public servant and a private tycoon. That has not stalled the process so far, but it will certainly give regulators and observers one more thing to talk about as the paperwork moves forward.
The Caesars-Fertitta transaction also has to be understood in the context of a gaming industry that is consolidating at an extraordinary pace. This is the largest casino merger since Eldorado Resorts acquired Caesars itself in 2020 for $17.3 billion. That deal, completed in the middle of the pandemic, was widely seen as a bet on the resilience of the American consumer and the enduring appeal of Las Vegas. That bet largely paid off, but it also loaded Caesars with significant debt and made the company a natural candidate for further restructuring. Now, with Fertitta stepping in, the company that was once a buyer has become a seller, and the deal that once made Caesars the survivor has made it a takeover target. What is more, the appetite for mega-deals in the casino industry has not faded. Earlier this year, investor Barry Diller announced an $18 billion buyout of MGM Resorts International, another enormous transaction that, if completed, would reorder the upper ranks of American gaming. Taken together, these deals suggest that the casino business is entering an era of billionaire matchmaking, where scale, data, and cross-brand loyalty are the ultimate prizes. The logic is clear: bigger companies can invest more heavily in technology, sports betting platforms, and customer analytics. They can market across more properties, squeeze better deals from vendors, and ride out economic downturns more easily than smaller, independent operators. For shareholders, these consolidation waves are often welcome, because the premiums are hard to ignore. For consumers, the verdict is more complicated. Fewer owners can mean fewer price wars, more uniform service standards, and less variety in everything from hotel décor to gambling promotions. For now, though, the momentum is unmistakable. The industry is moving toward larger and larger entities, and the Caesars-Fertitta combination is one of the clearest expressions yet of that trend.
So what happens now? The shareholder vote resoundingly clears the first hurdle, but it does much more than simply check a box on a corporate checklist. It sends a clear signal to regulators, employees, competitors, and the wider public that the Fertitta era at Caesars is not a hypothetical scenario or a remote possibility; it is happening. The money has spoken, and it has said yes. For shareholders, the result is a clean, fixed price with a substantial premium attached. For the roughly 60 casinos that would come under the combined company’s control, the future will involve integrating brands, payroll systems, loyalty programs, and management styles. For local communities in places like Stateline and Laughlin, where the deal would concentrate ownership in the hands of a single corporate player, the coming months will bring both hope and concern. The next step is the regulatory gauntlet, with Nevada’s gaming authorities taking center stage. Federal antitrust reviews will also have to run their course, and the timing will likely stretch into next year. If those approvals come through, the acquisition will close, and the Golden Nugget and Caesars brands will begin the long, intricate process of living under one roof. Tilman Fertitta will have to balance his diplomatic responsibilities in Rome with the enormous work of merging two business cultures, but his track record suggests he enjoys exactly this kind of challenge. The vote gave him a mandate, and now he has to build. The next few months will be filled with paperwork, backroom negotiations, and regulatory hearings. But with roughly two-thirds of voting shareholders behind him and a quorum exceeding 70 percent of the company’s shares, Fertitta can move forward with a powerful sense of purpose. This is a story that is still being written, and the final chapters will depend on decisions made far away from neon lights and casino floors. For Caesars, for Fertitta, and for the entire landscape of American gambling, the future just got a little clearer—and a lot more interesting.