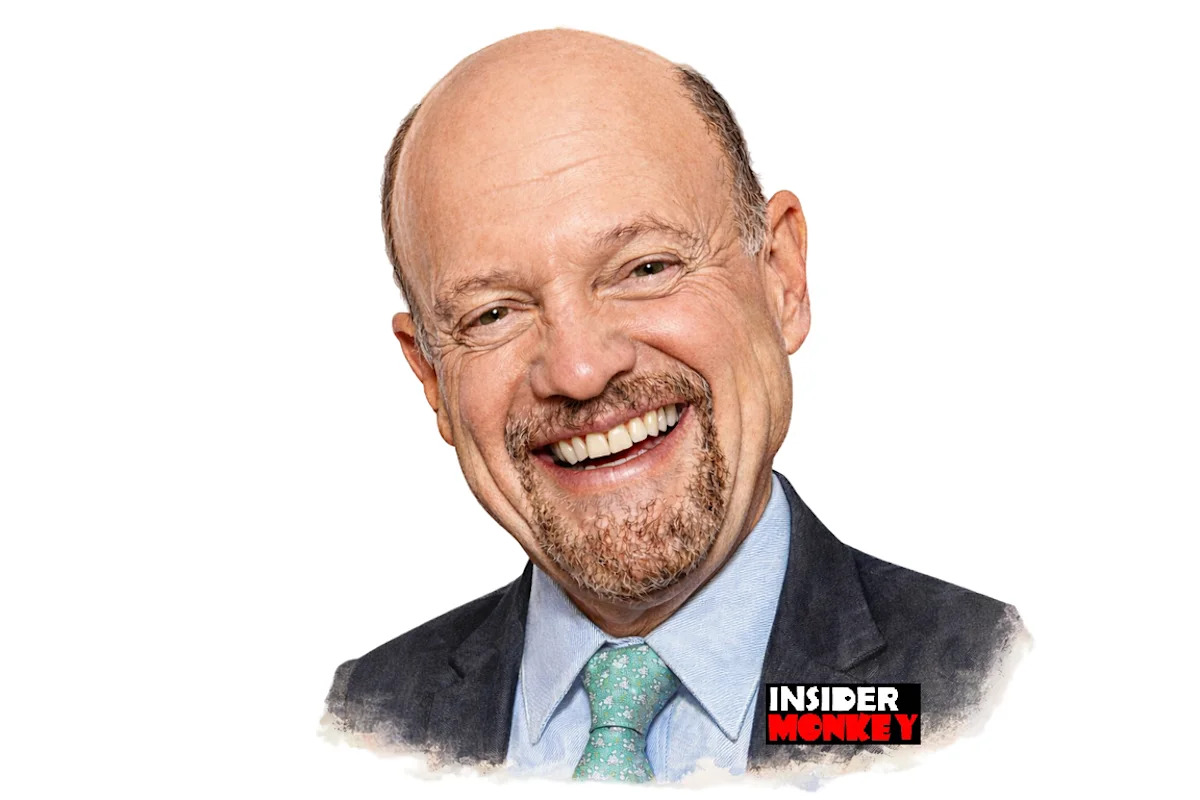
Imagine you’ve been watching a once-beloved company’s stock slide for months. Every headline seems to bring another layer of gloom, another reminder that the market has lost faith. That’s what it has felt like for Adobe (NASDAQ:ADBE), whose shares have fallen more than 27% over the past year. Then, on a seemingly ordinary Friday, the stock finally closed up 1.4%—not a massive rally, but enough to feel like a deep breath after being underwater for so long. The day was far from quiet, though. It was actually jam-packed with analyst opinions and social media buzz that perfectly captured the mixed emotions surrounding the company. On one side, Morgan Stanley came out and recommended selling the stock, maintaining an Underweight rating and a $240 price target after Adobe’s third-quarter earnings report. On the other side, Jim Cramer took to social media with his characteristic flair, suggesting that the recent cuts in Adobe felt “false” and wondering aloud whether a short squeeze could develop. He even tweeted “Good squeeze up in Adobe” as the stock moved higher. The whole situation paints a picture of a company at a crossroads, with bulls and bears tugging at the narrative, and everyday investors trying to figure out which side makes more sense.
When you dig into the numbers Adobe actually posted, the earnings were modestly impressive, at least at first glance. The company reported revenue of $6.76 billion and earnings per share of $6.13, both slightly above what Wall Street had expected—analysts were looking for $6.70 billion in revenue and $6.09 in earnings per share. On a purely mechanical level, that’s a beat, and in a normal environment, it might have led to a more enthusiastic reaction. But Adobe’s situation isn’t normal, because the market is wrestling with a bigger question: what happens to a company whose products are being threatened by the very AI revolution it helped popularize? The central debate is whether users will continue paying for Adobe’s creative software when they can increasingly generate their own designs, images, and even full marketing campaigns using AI tools. That uncertainty has weighed heavily on the stock, and it explains why a mild earnings beat didn’t instantly erase the pessimism. For long-term investors, the key metric to watch isn’t just revenue or earnings, but whether Adobe’s own AI initiatives can generate enough new business to offset any cannibalization of its traditional creative cloud subscriptions. The company’s AI-related annual recurring revenue (ARR) was the standout number in the report, and it absolutely demands attention.
Let’s talk about that AI ARR, because it really is a bright spot. Adobe’s AI annual recurring revenue jumped by a remarkable 150% year over year, landing at $650 million in the third quarter. That’s not a rounding error, and it suggests that the company’s bet on generative AI isn’t just a defensive move—it’s actually starting to produce meaningful revenue. Drilling down a little further, Adobe’s AI-powered platforms Firefly and GenStudio posted ending ARR growth of 40% and 20%, respectively. Overall ARR, which measures recurring revenue across the business, grew by 11% annually to $27.50 billion. During the quarter, Adobe also crossed a major milestone: more than one billion monthly active users (MAUs) for the first time in its history. Put all of those numbers together, and there’s a reasonable argument that the worst of the AI impact might be behind the company. Yes, the fear has been that AI substitutes for human creativity would undercut Adobe’s pricing power, but the growth in its own AI products suggests the company is finding ways to participate in the disruption rather than just being disrupted by it. For investors who have watched Adobe get punished for AI fears all year,