When a factory burns down, the first thing an insured business wants is a fair, speedy settlement from its insurance company. But what happens when the insurer investigates and concludes that the claim itself is built on falsehoods? That was the central question in a recent Supreme Court case involving a paper-board manufacturer and New India Assurance Company. The story starts with a devastating fire in May 2009 at a factory in Najibabad, where the company manufactured paper boards from waste paper. The factory held two fire insurance policies—one covering stock, the other covering buildings, plant, and machinery. After the fire tore through the waste-paper yard, damaging raw material and a tin shed, the insured company filed a claim seeking over ₹7.31 crore, plus interest. The insurer, however, did not simply pay. It appointed a preliminary surveyor, then an investigative agency, and then a final surveyor. Each of them raised serious questions about the authenticity and size of the loss. The insurer ultimately rejected the claim, saying the policy conditions had been violated. The insured company then went to the National Consumer Disputes Redressal Commission (NCDRC), which surprised everyone by awarding ₹2.4 crore, along with interest and additional compensation for delay and costs, while essentially ignoring the surveyors’ negative findings. The Supreme Court later stepped in to overturn that award, and in doing so, delivered an important lesson about the power of surveyor reports and the consequences of making a false insurance claim.
The dispute was not about whether a fire occurred—it clearly did. The real fight was about whether the insured company was telling the truth about how much stock was destroyed and whether the claim was grossly exaggerated. According to the facts laid out in the judgment, the insurer’s preliminary surveyor immediately flagged the need for a meticulous investigation to rule out a deliberate fire and a hypothetical loss. The independent investigative agency that was then brought in found the cause of the fire unclear and described various aspects of the account as improbable. The final surveyor went even further, documenting a series of abnormalities that pointed to an inflated and unsubstantiated claim. For example, the final surveyor noticed that the burnt debris and the condition of the tin shed did not match the amount of usable stock the insured claimed had been destroyed. The raw-material consumption and yield figures were not supported by any reliable records and were highly improbable. There was no proper system for weighing or tracking the waste paper, and the reported yield was described as imaginary. Even the workers’ statements did not support the story that a genuine effort had been made to fight the fire. Taken together, these findings led the insurer to repudiate the claim entirely, arguing that the insured had violated policy conditions that require honesty and that void claims supported by false statements. The insured, however, maintained that the fire was real and the loss genuine, and it took its case to the consumer commission.
The Supreme Court’s judgment is rooted in a well-established legal principle about the status of a surveyor’s report. Under Section 64-UM of the Insurance Act, 1938, a surveyor is not just a random expert hired by the insurer; the appointment is governed by statute, and the surveyor is bound by a code of conduct. The report prepared by a surveyor carries evidentiary value, meaning it cannot be treated as a mere suggestion or a piece of paper that can be brushed aside at will. While an insurer is not absolutely bound to accept a surveyor’s report and can appoint a second surveyor for satisfactory reasons, the report cannot be discarded arbitrarily—neither by the insurer nor by a consumer forum. The Supreme Court explained that this principle has a direct consequence for consumer forums. When an insurer repudiates a claim based on survey reports that negate the claim on factual grounds, the insured person or company must, in its complaint, specifically plead and prove a deficiency in those reports. A vague allegation that the surveyors got it wrong is not enough. The insured must point to a specific, statutorily-recognised flaw in the surveyor’s work—such as a failure to follow the code of conduct, an error in methodology, or a clear bias—before the report can be set aside. In this case, the insured had done no such thing. Yet the NCDRC had simply discarded both surveyor reports and substituted its own assessment of the loss. The Supreme Court found this approach to be wholly unjustified and contrary to the legal framework.
Looking at the facts, the Supreme Court found that the material strongly pointed to a false and inflated claim. The final surveyor had recorded multiple red flags that undermined the insured’s version of events. The burnt debris and the state of the tin shed were inconsistent with the presence of the usable stock that the insured claimed was destroyed. The raw-material consumption and yield figures were unsupported by any credible records and were highly improbable. There was no proper system of weighing or recording waste paper, making it impossible to verify the actual quantity of raw material on hand. The reported yield was described as imaginary, and the workers’ statements did not corroborate the claim that there was a genuine attempt to control the fire. In the Supreme Court’s view, these were not minor discrepancies or technical failures; they were false assertions made to pressure the insurer into paying far more than the actual loss. The Court quoted a key principle: “If an insured makes false averments to bolster its claim, contrary to the policy conditions, the insurer would be lawfully entitled to reject such claim on that ground without further ado.” This is a powerful statement because it confirms that insurance policies are not just financial contracts—they are contracts of good faith. When an insured party exaggerates or fabricates details, it breaks that faith, and the insurer has every right to refuse payment. The Court also noted that the NCDRC had no basis to give the insured a clean chit, to hold that there was no delay in informing the fire station, or to undertake its own independent assessment of the loss and quantify it at a figure far beyond what the surveyors found. All of that exceeded the consumer commission’s role.
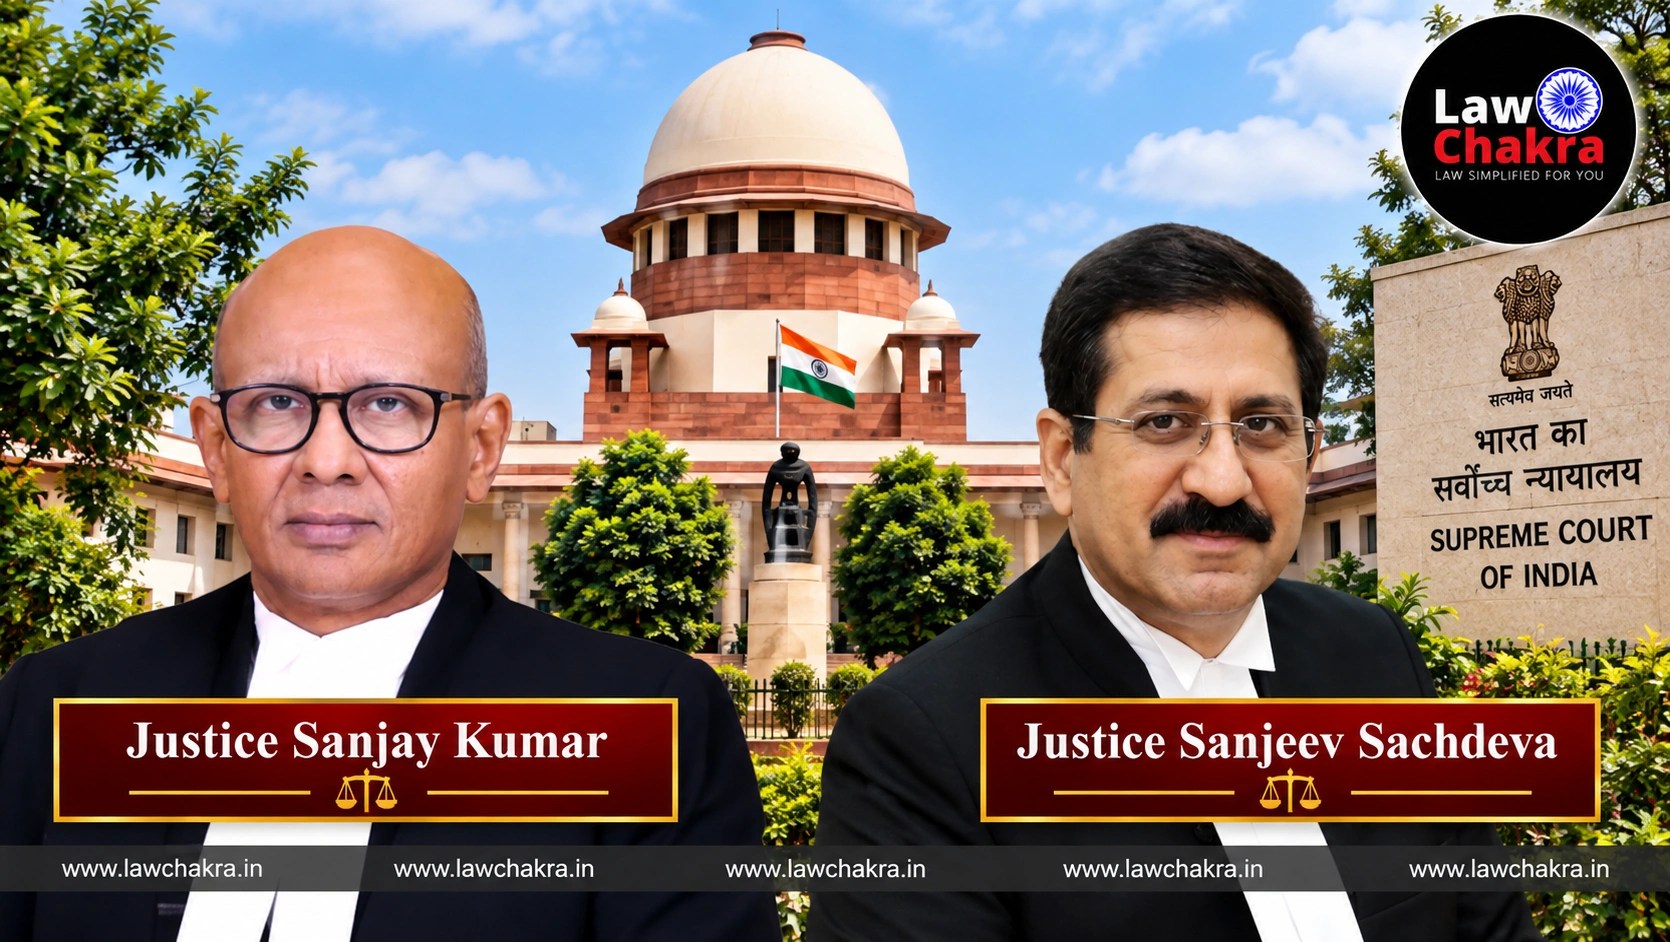
The outcome of the case was clear and decisive. The Supreme Court allowed the insurer’s appeal and set aside the NCDRC’s order that had directed New India Assurance to pay ₹2.4 crore with interest, along with ₹3 lakh for deficiency in service and ₹1 lakh in costs. The insured’s cross-appeal, which had sought an even higher amount of compensation, was dismissed. As a further consequence, the Court directed that any amounts the insurer had deposited in connection with the proceedings—presumably to comply with earlier orders—should be returned to the insurer with accrued interest. The judgment was authored by Justice Sanjay Kumar and delivered by a Bench that also included Justice Sanjeev Sachdeva. The reasoning was straightforward: the surveyors had done their job, they had found nothing that supported the insured’s version, and their reports had not been credibly challenged by the insured. The consumer commission had no authority to ignore those reports and act as a super-surveyor, coming up with its own loss figures. In doing so, it had unjustly penalised the insurer and rewarded a claim that the evidence showed to be false and inflated. The Supreme Court’s decision restores the balance and reminds all parties involved—insurers, insureds, and consumer forums—that the law cannot be used to shield dishonesty.
The broader significance of this judgment extends well beyond the specific factory in Najibabad. It reasserts the disciplined role that consumer forums must play when dealing with property and fire insurance claims that have been repudiated based on surveyor reports. A surveyor’s report is not an optional professional opinion that a forum may accept or reject at its whim; it is a statutorily contemplated document with evidentiary value, and a claimant who wants it ignored must identify, with specific particulars, where the report falls short of the statutory standard. If a consumer forum discards such reports merely because it is dissatisfied with the outcome, or because it sympathises with the claimant, it exceeds the bounds of its adjudicatory function. That was exactly the vice the Supreme Court identified in the NCDRC’s order. The other important lesson is about the consequences of a false claim. Fire and property policies routinely contain clauses that void a claim if it is fraudulent or supported by false statements, and they require the insured to substantiate its loss. Courts have given those clauses effect for good reason: insurance exists to share genuine risk, not to provide a windfall to dishonest claimants. Where surveyors found that the claimed stock could not have been present, that consumption and yield figures were unsupported, and that the account of the fire did not hold together, the insured’s claim clearly fell into the category of false and inflated, and the insurer was entitled to reject it outright. But this decision should not be read as a license for insurers to reject claims on thin grounds. The same body of law protects genuine claimants, and consumer forums have repeatedly struck down repudiations based on trivial or wrongful reliance on technicalities. What this case decides is the narrower proposition that a claim shown, on the surveyors’ unrebutted findings, to be false and inflated cannot be salvaged by a consumer forum’s willingness to overlook those findings. The protection that consumer law affords runs to honest claims, not fabricated ones. In that sense, the judgment is a reminder that fairness cuts both ways: the insured must be honest, the insurer must be fair, and the consumer forum must respect the evidence before it.